Financial Survival Guide After a Layoff: Cash Flow, Benefits & Emergency Planning
Actionable financial strategies to navigate a layoff, from managing immediate cash flow and severance to auditing expenses, securing health coverage, and managing retirement accounts.
Financial Survival Guide After a Layoff
A sudden layoff creates immediate financial disruption by halting earned income.
Note: This guide uses U.S. examples and regulatory frameworks; unemployment benefits, healthcare options, employment laws, severance requirements, and retirement account rules vary by state, employer, plan, and individual circumstances.
When facing job loss, your primary objective is protecting cash flow, liquidity, health coverage, and essential obligations—rather than making rushed long-term decisions. Learning what to do financially after a layoff requires executing a structured triage plan to maintain stability.
Executive Summary: Layoff Action Plan
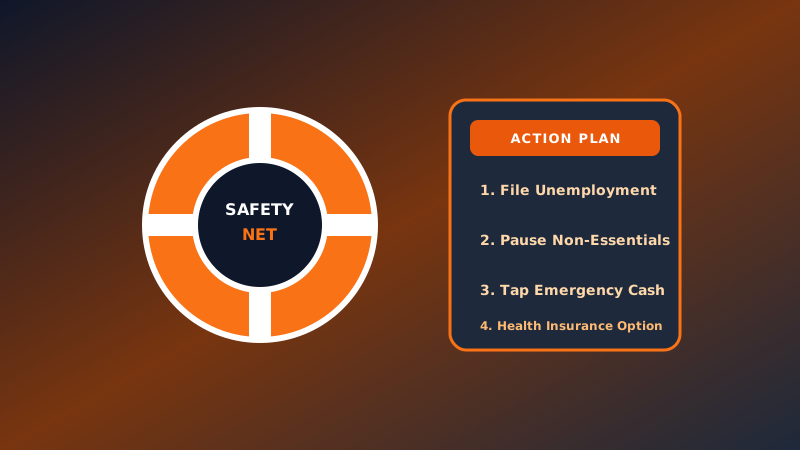
- First 48 Hours: Secure final paycheck details, collect benefit documents, review severance terms, and document PTO handling.
- Cash-Flow Triage: Transition immediately to an essential-only budget to preserve liquid cash reserves.
- Unemployment & Healthcare: File for state unemployment insurance promptly and evaluate COBRA versus ACA Marketplace health coverage options.
- Retirement Accounts: Avoid rushed 401(k) cash-outs that trigger income taxes and early withdrawal penalties.
- Written Documentation: Keep detailed records of employer communications, agreements, and benefit notices.
1. The First 48 Hours: Immediate Financial Checklist
Complete this 48-hour checklist:
- Confirm Final Paycheck Details: Verify final paycheck timing, including earned wages and commissions.
- Collect Benefit Documents: Download health summaries, retirement statements, life insurance certificates, and tax documents (W-2s/pay stubs).
- Identify Severance Information: Obtain written copies of proposed separation agreements.
- Review Unused PTO Handling: Check company policy and state rules regarding PTO payouts.
- Determine Health Coverage End Date: Clarify the date employer health insurance terminates.
- Review Bank Balances & Bills: Audit liquid cash against scheduled auto-payments over the next 30 days.
- Pause Discretionary Spending: Immediately suspend nonessential recurring subscriptions and convenience spending.
- Preserve Tax & Employment Records: Keep copies of job descriptions, performance reviews, and separation notices.
Note: Employers are not universally required to offer severance pay or PTO cash-outs unless mandated by state law, contracts, or company policies.
2. Severance and Separation Agreements
Severance packages provide transition support, but separation agreements frequently include binding legal terms.
Structure & Terms
Severance may be paid as a lump sum or periodic payroll payments. Agreements typically require signing a release of claims, alongside confidentiality, non-disparagement, or non-solicitation covenants.
Read separation documents thoroughly. Because employment laws differ across jurisdictions, seeking legal review before waiving legal rights is appropriate when evaluating agreements.
3. Unemployment Benefits
Unemployment insurance (UI) is a joint federal-state program providing temporary partial income replacement to eligible workers unemployed through no fault of their own.
Key Factors in Unemployment Claims
- State Variations: Eligibility criteria, weekly benefit amounts, maximum durations, waiting periods, and filing procedures vary by state.
- Work-Search Requirements: Most states require claimants to document weekly job-search activities to maintain eligibility.
- Disqualifying Circumstances: Benefits may be denied if separation is voluntary resignation without good cause or termination for severe misconduct.
According to U.S. Department of Labor (DOL) guidelines, claimants should file through state unemployment agencies immediately, as processing times span several weeks.
4. Health Insurance After Job Loss
Losing employer health coverage creates an urgent need to secure continuous medical insurance.
Major U.S. Coverage Paths
- COBRA Continuation Coverage: COBRA permits remaining on your former employer's group plan. However, participants typically pay 100% of the total premium plus a 2% administrative fee, making it expensive.
- ACA Marketplace Plans: Job loss triggers a 60-day Special Enrollment Period (SEP) on HealthCare.gov or state exchanges. Depending on income, buyers may qualify for premium subsidies.
- Spouse/Household Plan: Joining a spouse’s employer plan during a Special Enrollment Period is often cost-effective.
Evaluate total costs—including premiums, deductibles, copays, and networks. ACA plans are often more affordable than COBRA, as highlighted in DOL and HealthCare.gov guidelines.
5. Cash-Flow Triage After a Layoff
Managing finances after job loss requires a framework for how to manage money after losing a job. Categorize expenses into three tiers:
- Tier A: Essential: Housing (rent/mortgage), utilities, groceries, health insurance, basic transit, and minimum required debt payments.
- Tier B: Important / Adjustable: Mobile phone plans, internet speeds, and service contracts.
- Tier C: Nonessential: Dining out, streaming subscriptions, retail purchases, and upgrades.
Preserving liquid cash provides breathing room. This triage approach aligns with auditing your monthly expenses and implementing the 50/30/20 budgeting rule while relying on an emergency fund.
6. What to Do With a 401(k) or Other Retirement Account
Evaluating what to do with a 401(k) after leaving a job involves four choices:
- Leave Money in Former Plan: Permitted by many employers if account balance minimums are met.
- Roll Over to New Employer Plan: Transfer funds into a new 401(k) if available.
- Roll Over to an IRA: Transfer assets into an IRA, maintaining tax-deferred status.
- Cash Out: Withdraw funds as a cash distribution.
Tax Warnings
Cashing out triggers income tax. According to IRS Publication 575, early withdrawals before age 59½ generally incur an additional 10% federal penalty tax. When rolling over, request a direct trustee-to-trustee transfer to avoid mandatory 20% tax withholding, as detailed in tax-advantaged retirement accounts.
7. Other Employee Benefits to Review additional employee benefits requiring action following separation:
- Life & Disability Insurance: Group term policies often end upon termination, though some offer conversion rights.
- FSA vs. HSA Accounts: Healthcare FSAs operate on a "use-it-or-lose-it" basis upon separation. HSAs belong to the individual and remain portable.
- Equity & Stock Options: Review vesting schedules and option exercise windows (often 90 days post-termination).
- Outplacement Services: Utilize employer-paid career coaching or placement tools if provided.
8. Protecting Your Job-Search Finances
Conducting a job search incurs expenses. Create an emergency budget after job loss allocating funds for essential tools:
- Technology & Connectivity: Reliable internet and phone access.
- Professional Attire & Training: Interview clothing and industry certifications.
- Networking Expenses: Transit or association event fees.
Balancing frugality with job-search tools ensures effectiveness without depleting reserves.
9. Layoff Financial Recovery Checklist
Complete this recovery checklist:
- Confirm Final Paycheck & PTO: Verify wage calculations and time off payments.
- Review Severance Terms: Examine separation agreements and consult legal counsel if needed.
- File Unemployment Claim: Submit your application through your state unemployment office.
- Select Health Coverage: Compare COBRA, ACA Marketplace, and spouse coverage within 60 days.
- Execute Cash-Flow Triage: Cut nonessential spending and prioritize essential housing and food costs.
- Contact Lenders Proactively: Request hardship programs or payment deferrals before missing payments.
- Decide on Retirement Assets: Initiate direct trustee-to-trustee rollovers for 401(k) accounts.
- Check HSA/FSA & Equity: Review option exercise deadlines and spend remaining FSA balances where eligible.
- Organize Job-Search Budget: Allocate modest funds for networking, technology, and interview prep.
- Maintain Document Records: File separation notices, tax records, and unemployment confirmations.
Conclusion
The core objective during a layoff is protecting liquidity, securing health coverage, utilizing available benefits, and avoiding rushed decisions. Taking structured steps preserves your financial foundation so you can focus on securing your next role.
Sources
- U.S. Department of Labor (DOL): Unemployment Insurance Program & Health Guidance https://www.dol.gov/general/topic/unemployment-insurance
- HealthCare.gov (CMS): Special Enrollment Periods & Job Loss Options https://www.healthcare.gov/coverage-outside-open-enrollment/special-enrollment-period/
- Internal Revenue Service (IRS): Publication 575 (Pensions & Annuities) https://www.irs.gov/publications/p575
Disclaimer
Educational content only. Unemployment benefit rules, healthcare options, labor laws, severance requirements, tax regulations, and retirement account choices vary significantly by state, employer, plan, and individual circumstances. Consult a qualified CPA, employment attorney, or financial advisor for personalized guidance.
MoneyTalkin' provides financial education, educational concepts, and general informational guides. Articles do not constitute personalized financial, investment, legal, or tax advice. Financial products, rates, terms, and regulatory rules change frequently; consult a qualified financial professional regarding your specific situation. Read our full Disclaimer Policy.
Written by MoneyTalkin'
MoneyTalkin' researches and publishes objective financial education content, money management fundamentals, and practical financial guides.
Related Technical Articles
Explore related topics in this cluster to deepen your understanding.